Planning your next caravan adventure? Explore potential repayment scenarios with our Caravan Loan Repayment Calculator. Adjust loan amounts, interest rates and repayment terms, and view amortisation charts to better understand potential repayments and interest costs over time.
Calculator results are estimates only and not quotes. Actual quotes will be provided by licensed brokers after you submit an enquiry.
Caravan Loan Details:
Important!
Caravan Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.). To find out if you qualify ... and for a free, personalised interest rate and repayment quote, please CLICK HERE
Caravan Loan Amortisation Calculator
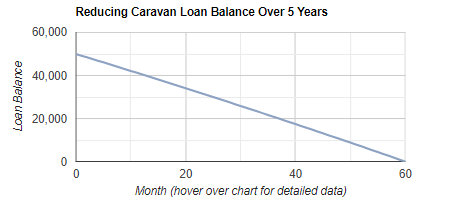
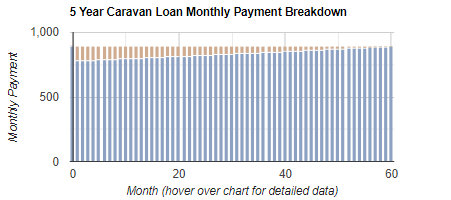
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Caravan Loan Repayment Calculator
Our Caravan Loan Repayment Calculator helps you estimate your likely monthly caravan loan repayments, understand how much interest you may pay over time, and visualise your loan via amortisation charts. It’s important because small changes to your purchase price, deposit, loan term or interest rate can materially affect cash flow and the total cost of caravan finance, helping you plan a realistic budget before you apply.
How to complete the form for the best result
1. Purchase Price
Enter the full caravan purchase price you expect to finance. If you plan to roll costs into the loan, consider adding likely upfront expenses such as registration, insurance and other on-road costs (where applicable). Use whole numbers only (no decimals or commas) to match the calculator format.
2. Deposit or Trade-in Value (if applicable)
Add any cash deposit and/or the trade-in value of an existing caravan. If you have no deposit or trade-in, leave this field blank. A higher deposit generally reduces the amount borrowed and can lower repayments and total interest.
3. Term of Loan (years)
Select the number of years you want to repay over. Longer terms usually reduce monthly repayments but increase the overall cost of the loan due to more interest over time. Choose a term that fits your budget with a buffer for rate rises and living costs.
4. Interest Rate (percent per annum)
Select an interest rate to simulate. The listed range is indicative only and your actual rate can only be confirmed after you apply, based on factors like credit history and employment.
5. Calculate
Click calculate to generate your estimated repayment and amortisation charts.
How to interpret the results
1. Repayment estimate
Use the monthly repayment figure as a budgeting guide, then compare scenarios by adjusting the term, deposit and interest rate.
2. Amortisation charts
The loan balance chart shows how your debt reduces month by month. The interest versus principal chart highlights that early repayments typically include a higher interest portion, with more of each payment going to principal later in the term.
Important information (ASIC-style general guidance)
Results are estimates and do not constitute a quote. They may not include fees, charges, or lender-specific features. This information is general and does not consider your objectives, financial situation or needs. Consider whether a caravan loan is appropriate for you and seek personalised advice if required. Credit is subject to approval and terms and conditions.
A newly published Life Code Compliance Committee sanction has highlighted a practical but often overlooked issue for Australians relying on personal insurance: having a claim accepted is not the same as receiving every benefit correctly calculated and paid. The de-identified case, published on 16 November 2026, concerned an unnamed life insurer that underpaid about $1.6 million, including interest, across 66 income protection and death benefit claims. - read more
A NSW parliamentary inquiry into the state of live music has put public liability insurance back in the spotlight for venues, festivals and event operators, after its final report identified insurance affordability as a significant operating pressure and recommended further work on reform options. - read more
A NSW parliamentary inquiry into the state of live music has put insurance affordability back in the spotlight, with its final report tabled on 9 November 2026 identifying public liability insurance as a major cost burden for venues and festivals. The recommendation does not change premiums immediately, but it gives business owners a useful signal: governments, insurers and industry groups are still grappling with how public-facing risks are priced, documented and managed. - read more
The Insurance Council of Australia’s expanded Significant Event declaration for severe storms in Queensland and New South Wales is a timely reminder that insurance is tested in the messy aftermath of damage, power loss and disruption, not just at renewal time. By 17 November 2026, insurers had received more than 7,500 claims linked to severe weather from 11 to 17 November, with damage ranging from torn roofs and broken fences to water entry, hail impacts and spoiled food after outages. - read more
A recent business interruption dispute involving a bakery has given restaurant and cafe operators a timely reminder that disruption does not always start inside the insured premises. The Australian Financial Complaints Authority found in favour of a bakery retail business after its insurer declined a claim linked to a fire at the premises of its sole supplier, bringing supplier-dependency wording into sharp focus for hospitality businesses that rely on specialist producers, central kitchens, roasters, wholesalers or delivery partners. - read more
Caravanning is a popular pastime for many Australians, offering the freedom to explore the great outdoors and travel at leisure. However, owning a caravan comes with its own set of responsibilities and risks. - read more
Owning a caravan opens up a world of adventures across Australia, but it also brings certain risks. Having the right caravan insurance is essential for protecting your investment against accidents, theft, and unforeseen events. The importance of caravan insurance cannot be overstated for Australian owners, given the unique challenges presented by travel and storage conditions across various terrains and climates. - read more
Caravanning has become a favorite pastime for many Australians, offering a unique sense of freedom and the thrill of exploring the vast beauty of the country. The wanderlust associated with hitting the road and setting up camp wherever you choose speaks to a growing number of adventure-seekers. - read more
Planning to live on the road or tour Australia for months at a time? Learn how full-time caravan travel, storage addresses, contents, annexes, modifications and usage declarations can affect caravan insurance options. - read more
Caravan insurance is an important investment for anyone who owns a caravan, whether it's a touring caravan or a static caravan. Caravan insurance is designed to protect you financially in the event of theft, damage, or accidents. However, not all caravan insurance policies are created equal, and it's essential to choose the right policy to ensure you're adequately covered and get the best value for your money. - read more
Knowledgebase
Incontestability Clause: A provision in a life insurance policy that prevents the insurer from voiding coverage due to a misstatement by the insured after a certain period.